November 1, 2026
Buying a Home
How Much Can I Borrow for a Mortgage?
How much can I borrow for a mortgage? Lenders typically cap it at around 4.5 times income. Here’s how income, debts, a joint application and your deposit change it.
How much can I borrow for a mortgage? As a rough guide, MoneyHelper says lenders typically cap borrowing at four and a half times your annual income, and most people are offered less. The exact amount depends on your income, your outgoings, your credit history and the lender’s own rules.
This guide explains how lenders work out what you could borrow, what counts as income, how debts and a joint application change things, where your deposit fits in, and why the most you’re offered isn’t always the amount worth borrowing.
Key points
- Lenders typically cap borrowing at around 4.5 times your yearly income, and most people are offered less.
- Lenders look at your income, outgoings, credit file and how secure your job is, not just a multiple.
- Regular debts, such as loans, car finance and credit cards, can reduce what you could borrow.
- If you buy with someone else, lenders look at both incomes, and you’re each responsible for the whole mortgage.
- Your deposit doesn’t change the income multiple, but it does change the price you could pay and your loan-to-value.
4.5 timesincome, the typical cap on borrowing
About 15%of new mortgages can be at 4.5 times income or more
3 monthsof spending to aim for as a savings buffer
How much can I borrow? The quick answer
Lenders often start with your loan-to-income ratio. MoneyHelper explains that this is worked out by dividing the amount you want to borrow by your annual income, plus the income of anyone you’re buying with.
The most you can borrow is usually capped at around 4.5 times your income, but MoneyHelper is clear that this isn’t guaranteed and most people are offered less. The table below shows what 4 and 4.5 times income would look like at different income levels.
| Yearly income | 4 times income | 4.5 times income |
|---|---|---|
| £30,000 | £120,000 | £135,000 |
| £40,000 | £160,000 | £180,000 |
| £50,000 | £200,000 | £225,000 |
| £70,000 (two people combined) | £280,000 | £315,000 |
These figures are illustrative only. They don’t take any debts or outgoings into account, and a lender could offer you more or less.
How lenders decide how much you can borrow
An income multiple is only a starting point. MoneyHelper says lenders decide how much you can borrow by looking at your income, your outgoings and the security of your employment. They’ll also run a credit check when you make a full application.
Affordability rules lenders must follow
Lenders have to check that a mortgage is affordable for you under the Financial Conduct Authority’s (FCA) responsible lending rules. The FCA says that unless a mortgage’s interest rate is fixed for five years or more, lenders must consider likely future interest rate rises when they assess affordability.
Until 2022, the Bank of England also set a specific “stress test” that lenders had to use. Its Financial Policy Committee withdrew that test from 1 August 2022, but the FCA’s affordability rules still apply. As MoneyHelper puts it, your lender will still have its own rules to review your application.
The limit on high loan-to-income lending
The Bank of England also keeps a limit on how much lending happens at 4.5 times income or more. Under its latest rules, which took effect on 28 October 2026, the aim is to keep this to around 15% of new mortgages across the whole market. So some people can borrow more than 4.5 times their income, but it’s limited.
What counts as income?
MoneyHelper lists the types of income lenders may take into account:
- your basic income
- overtime, commission or bonus payments
- income from a second job or freelance work
- income from a pension or investments
- child maintenance and financial support from an ex-partner
Income multiples are normally worked out on your gross income, which is your pay before tax and National Insurance. Lenders then look at your take-home pay and outgoings to check the payments are affordable. They also set their own rules on how much of each type of income they count. For example, some may only count part of a bonus, or ask to see that overtime is regular. If you’re self-employed, MoneyHelper says lenders usually ask for two to three years’ accounts, and a tax return form SA302 if you have earnings from more than one source.
How outgoings and debts affect what you can borrow
Lenders look closely at what you already spend each month. MoneyHelper lists the outgoings they’ll ask about, including:
- credit cards, loans and credit agreements, such as a car lease
- child maintenance payments
- bills, such as water, gas, electricity, phone and broadband
- Council Tax, buildings insurance and other property charges, such as service charges and ground rent
They may also ask you to estimate regular spending, such as travel, food shopping and subscriptions. The more of your income that’s already committed, the less a lender is likely to lend.
Illustrative example
Income £40,000, with car finance of £300 a month.
A simple way to see the effect: take 12 months of the payment off your income. £40,000 − £3,600 = £36,400.
4.5 times £36,400 = £163,800, instead of £180,000.
Difference: about £16,200 less
This is the simple method our calculator uses to show the effect of debts. Lenders use their own, more detailed checks, so the real effect could be bigger or smaller.
Can two people borrow more than one?
Usually, yes. When you buy with someone else, lenders look at both of your incomes when they work out the loan-to-income ratio. They’ll also look at both of your outgoings and credit files.
A joint mortgage is a big commitment. MoneyHelper explains that with joint borrowing, you’re each agreeing to pay off the whole amount if the other person can’t or won’t pay. This is called joint and several liability. Joint borrowing also shows on both of your credit reports.
Does your deposit change how much you can borrow?
Your deposit doesn’t usually change the income multiple, but it changes two important things: the price you could pay, and your loan-to-value (LTV). LTV is the size of your mortgage as a percentage of the property’s value.
Illustrative example
You could borrow £180,000 and you have a £20,000 deposit.
£180,000 + £20,000 = a price of £200,000.
£180,000 ÷ £200,000 = 90% loan-to-value
MoneyHelper says most mortgages ask for a deposit of at least 5% to 10% of the price. A lower LTV can give you a wider choice of deals. Our guide to how much deposit you need to buy a home explains LTV bands in more detail.
%Loan-to-value calculatorWork out your LTV and how close you are to the next bandTry it →
Other things that can change the amount
Your mortgage term
The term is how long you take to pay the mortgage back. A longer term spreads the loan over more months, so the monthly payment is lower, which can make a bigger loan look more affordable in a lender’s checks. The trade-off is that you pay more interest overall. The FCA makes the same point about extending a term: it lowers payments but increases the total you pay back.
| £180,000 at 4.5% | Monthly payment | Total interest |
|---|---|---|
| 25-year term | about £1,001 | about £120,150 |
| 35-year term | about £852 | about £177,780 |
In this illustration, the longer term lowers the payment by about £149 a month but adds about £57,630 in interest. Lenders also set their own limits on how long a term they’ll offer.
Your credit history
Lenders check your credit file when you apply. MoneyHelper lists your credit history as one of the common reasons applications are turned down, and warns that applying for lots of credit in a short space of time can make it look like you have money problems. Checking your reports early gives you time to correct any mistakes before you apply.
Your type of work
Lenders look at how secure your job is, and MoneyHelper lists your employment history as another common reason applications are declined. If you’re self-employed, you’ll need to provide tax statements and business accounts, so lenders can see how steady your income has been.
Is the maximum mortgage worth borrowing?
The most a lender will offer you and the amount that’s comfortable for you aren’t always the same. MoneyHelper says there’s no specific percentage of income you should aim to spend on a mortgage, though people typically spend between 28% and 35% of their income on it.
It’s also worth thinking about what would happen if your circumstances changed. MoneyHelper suggests checking whether you could still pay if interest rates rose, if your income fell, or if you couldn’t work because of illness.
Illustrative example
£180,000 repayment mortgage over 25 years.
At 4.5%: about £1,001 a month.
At 6.5%: about £1,215 a month.
Difference: about £215 a month
These rates are for illustration only, not current market rates.
Borrowing less than the maximum could mean
- lower monthly payments and less interest overall
- more room in your budget if rates or bills go up
- more chance of keeping a savings buffer
But it can also mean
- a smaller price range when you’re house-hunting
- possibly needing a bigger deposit for the home you want
- a home that may suit you for a shorter time
Tip
MoneyHelper suggests aiming for savings that would cover about three months of spending, including your mortgage payments, in case your income drops unexpectedly.
How to get ready before you apply
- Check your credit reports MoneyHelper says it’s free, and checking your own report as often as you like won’t affect your score. There are four credit reference agencies: Experian, Equifax, TransUnion and Crediva.
- Bring your debts down where you can Lower monthly commitments can leave more room in a lender’s affordability check.
- Work out your budget Add up your regular spending, so you know what monthly payment would feel comfortable.
- Gather your documents Usually your last three months’ payslips, three to six months’ bank statements, your P60, ID and proof of your deposit.
- Get a mortgage in principle A written estimate of what a lender may be willing to lend you. It isn’t a guaranteed offer.
For the full picture of buying, see our guide to the home buying process step by step, and don’t forget to budget for the true cost of buying a house on top of your deposit.
Across the UK
The FCA’s affordability rules and the Bank of England’s lending limits apply across the UK, including Scotland, Wales and Northern Ireland. Lenders’ own criteria can still vary.
Important
Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it.
Summary
How much you can borrow for a mortgage usually starts with an income multiple of up to around 4.5 times, but lenders also look closely at your outgoings, debts, credit file and job security, and most people are offered less. Your deposit then decides the price you could pay. The maximum on offer may not be the most comfortable amount, depending on your circumstances.
Frequently asked questions
How do lenders decide how much I can borrow?
Lenders look at your income, your outgoings, how secure your job is and your credit file. Many start with a loan-to-income ratio, typically capped at around 4.5 times your yearly income. They must also check the mortgage is affordable under FCA rules, including considering future rate rises unless the rate is fixed for five years or more.
Can two people borrow more than one?
Usually, yes. Lenders look at both incomes when you apply together, so the amount you could borrow is often higher. They’ll also look at both people’s outgoings and credit files. You’d each be responsible for the whole mortgage, not just half, if the other person couldn’t or wouldn’t pay.
Do lenders use gross or net income?
Both, at different stages. Lenders normally work out income multiples using your gross income, which is your pay before tax and National Insurance. They then check affordability against your net, take-home pay and your outgoings. Each lender sets its own rules on which income it counts, such as overtime or bonuses.
Does my deposit change how much I can borrow?
Your deposit doesn’t usually change the income multiple, but it changes the price you could pay and your loan-to-value. A bigger deposit means a lower loan-to-value, which can open up a wider choice of deals. Most mortgages need a deposit of at least 5% to 10% of the price.
Should I borrow the maximum offered?
Not necessarily. The most a lender offers isn’t always the most comfortable amount for your budget. It’s worth checking you could still afford the payments if interest rates rose or your income fell, and keeping some savings as a buffer. What’s right depends on your circumstances.
Sources
- MoneyHelper – What mortgage can I afford?
- MoneyHelper – How much should I spend on a mortgage?
- MoneyHelper – How to apply for a mortgage
- MoneyHelper – Taking out a joint loan: what you need to know
- MoneyHelper – What to do when your mortgage application is declined
- MoneyHelper – How to check your credit report for free
- Financial Conduct Authority – The FPC’s mortgage market recommendations
- Financial Conduct Authority – Support available for mortgages as interest rates rise
- Bank of England – FPC confirms withdrawal of mortgage market affordability test
- Bank of England – PS19/26: High loan to income lending
Last updated: 2 November 2026. This guide is general educational information only and is not regulated financial advice.
Free reminder service
Is your fixed rate ending soon?
When a deal ends, most mortgages move onto the lender's standard variable rate, which is usually higher. We'll remind you in good time to look at your options.
- 1Tell us when your deal endsJust your first name, email, and the month and year
- 2We email you 6, 3 and 1 month beforeSo you have time to compare, without the rush
- 3Look at your options, no pressureOur guides and calculators are always free
Set up your free reminder
Takes under a minute. Unsubscribe any time.
Your reminder is set
We've sent a confirmation email. If it's not there in a few minutes, check your spam folder.
Mortgage Owl provides general educational information only, not regulated financial advice.
About the author: Steve
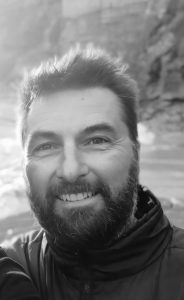
Steve is the founder of Mortgage Owl and is training to become a mortgage adviser. He’s currently studying Module 1 of 3 of CeMAP, the Certificate in Mortgage Advice and Practice.
He originally studied business, finance and accountancy, then spent 30 years in policing and the merchant navy before returning to his first passion: helping people make sense of money.
He writes every Mortgage Owl guide in plain English, so you can feel informed before you speak to an adviser.
Qualifications: Registered student with the London Institute of Banking & Finance (LIBF), studying for CeMAP.
He originally studied business, finance and accountancy, then spent 30 years in policing and the merchant navy before returning to his first passion: helping people make sense of money.
He writes every Mortgage Owl guide in plain English, so you can feel informed before you speak to an adviser.
Qualifications: Registered student with the London Institute of Banking & Finance (LIBF), studying for CeMAP.
Related guides
October 31, 2026
October 29, 2026