October 28, 2026
Mortgage News
Remortgaging Jumps Ahead of Thursday’s Bank Rate Decision
Remortgage approvals jumped to 42,600 in September as average rates edged up. Here’s what to know before Thursday’s Bank Rate decision.
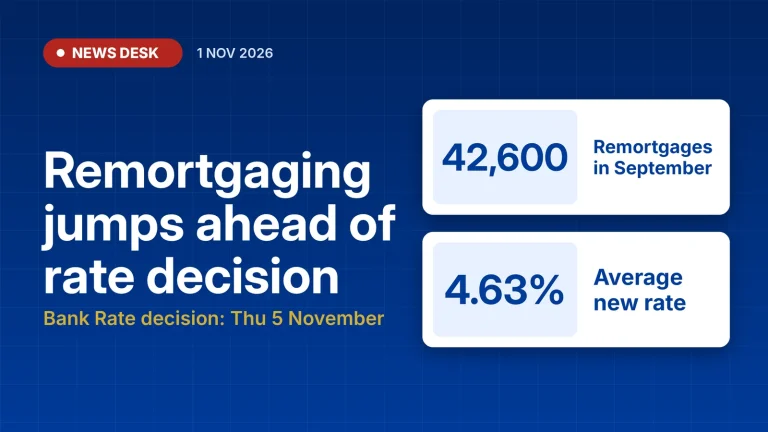
Ahead of this Thursday’s Bank Rate decision, new figures from the Bank of England show remortgaging jumped in September. Approvals for remortgaging rose to 42,600, up from 34,000 in August, while the average rate on new mortgages edged up to 4.63%. The Bank’s Monetary Policy Committee announces its next decision on Thursday 5 November 2026.
Here are the 5 things worth knowing if your fixed rate is ending, or you’re buying, taken from the Bank of England’s Money and Credit release published on 29 October 2026 and the Office for National Statistics’ latest inflation figures.
Key points
- Remortgage approvals rose to 42,600 in September, from 34,000 in August.
- Approvals for house purchases dipped to 53,400, from 54,800.
- The average rate on newly drawn mortgages rose to 4.63%, from 4.60%.
- Inflation rose to 3.5% in September, from 3.1% in August.
- Bank Rate is 3.75%. The next decision is on Thursday 5 November.
42,600remortgage approvals in September, up from 34,000
4.63%average rate on newly drawn mortgages
5 Novnext Bank Rate decision
1. Remortgaging jumped by about a quarter
Approvals for remortgaging, where someone moves their mortgage to a new lender, rose to 42,600 in September, up from 34,000 in August. That’s an increase of about 25%. The Bank of England notes these figures only capture remortgaging with a different lender, so people switching to a new deal with their existing lender aren’t counted.
2. Home-buying approvals dipped slightly
Mortgage approvals for house purchases, which the Bank of England describes as an indicator of future borrowing, fell slightly to 53,400 in September, from 54,800 in August. Net mortgage borrowing also eased, to £3.9 billion from £4.2 billion.
3. Average mortgage rates edged up
The average interest rate on newly drawn mortgages, known as the “effective” rate, rose to 4.63% in September, from 4.60% in August. The average rate on all outstanding mortgages rose to 4.03%, from 4.00%.
These are averages across all new lending, so the rate you’re offered will depend on your deposit, your circumstances and the type of deal.
4. Inflation rose to 3.5%
The Office for National Statistics reported that consumer price inflation rose to 3.5% in September, from 3.1% in August. Motor fuels made the largest upward contribution.
Inflation is one of the main things the Bank of England looks at when it sets Bank Rate. At its September meeting, the Monetary Policy Committee said it expected inflation to rise further, to about 3¾% in the last three months of 2026, and that the risks to the inflation outlook were “tilted to the upside”.
5. The Bank Rate decision is on Thursday 5 November
Bank Rate is currently 3.75%. At its last meeting, on 17 September 2026, the Monetary Policy Committee voted 6–3 to keep it there, with three members voting to raise it to 4%. The Committee said it “stands ready to act as necessary”.
What a Bank Rate change could mean for you
- Tracker mortgages usually follow Bank Rate, so payments could change soon after a decision.
- Standard variable rates (SVRs) are set by each lender and can change at any time.
- Fixed rates don’t change until your deal ends, but the deals on offer to new customers can change.
Nobody can know in advance what the Committee will decide. We’ll publish the result and what it means on the day.
£New payment calculatorSee what a different rate could mean for your monthly paymentTry it →
What this means for you
If your fixed rate ends in the next six months, you can usually arrange your next deal up to six months ahead, so it starts as soon as your current one finishes. Our guide to what happens when your fixed rate ends explains your options, and our remortgage guide covers the costs and timing.
If you’re buying, our guide to how much deposit you need explains how your deposit affects the rates you could be offered.
Sources
- Bank of England – Money and Credit – September 2026 (29 October 2026)
- Office for National Statistics – Consumer price inflation, UK: September 2026 (21 October 2026)
- Bank of England – Bank Rate maintained at 3.75% – September 2026
- MoneyHelper – Can I change my mortgage provider?
Published 1 November 2026. This bulletin reflects the figures published on the dates shown. It’s general educational information only and is not regulated financial advice.
Free reminder service
Is your fixed rate ending soon?
When a deal ends, most mortgages move onto the lender's standard variable rate, which is usually higher. We'll remind you in good time to look at your options.
- 1Tell us when your deal endsJust your first name, email, and the month and year
- 2We email you 6, 3 and 1 month beforeSo you have time to compare, without the rush
- 3Look at your options, no pressureOur guides and calculators are always free
Set up your free reminder
Takes under a minute. Unsubscribe any time.
Your reminder is set
We've sent a confirmation email. If it's not there in a few minutes, check your spam folder.
Mortgage Owl provides general educational information only, not regulated financial advice.
About the author: Steve
Steve is the founder of Mortgage Owl and is training to become a mortgage adviser. He’s currently studying Module 1 of 3 of CeMAP, the Certificate in Mortgage Advice and Practice.
He originally studied business, finance and accountancy, then spent 30 years in policing and the merchant navy before returning to his first passion: helping people make sense of money.
He writes every Mortgage Owl guide in plain English, so you can feel informed before you speak to an adviser.
Qualifications: Registered student with the London Institute of Banking & Finance (LIBF), studying for CeMAP.
He originally studied business, finance and accountancy, then spent 30 years in policing and the merchant navy before returning to his first passion: helping people make sense of money.
He writes every Mortgage Owl guide in plain English, so you can feel informed before you speak to an adviser.
Qualifications: Registered student with the London Institute of Banking & Finance (LIBF), studying for CeMAP.
Related guides

October 23, 2026
October 20, 2026