November 9, 2026
Mortgage News
Mortgage Deals Now Last Just 13 Days: What It Means If Your Fix Is Ending
Lenders are changing or withdrawing mortgage deals after an average of just 13 days. Here’s why, and what it could mean if your fixed rate ends soon.
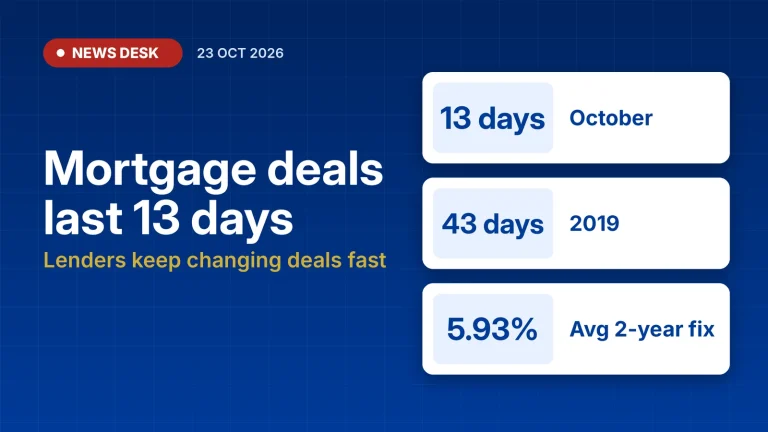
Mortgage deals are now staying on the market for an average of just 13 days before they are changed or withdrawn, according to Moneyfacts. That is down from 14 days in September and far below the 43 days seen in 2019. It means the deal you see today may not be there in a fortnight. If your fixed rate ends in the next few months, here is what is happening and what it could mean for you.
Key points
- The average mortgage deal lasted 13 days in October before being changed or withdrawn, down from 14 days in September (Moneyfacts).
- In 2019, the average was 43 days.
- Average two-year fixed rates rose from 5.59% to 5.93% between the start of September and the start of October.
- The Budget (28 October) and the next Bank Rate decision (5 November) could bring more changes.
What the figures show
Moneyfacts tracks how long the average mortgage deal stays available before a lender reprices or withdraws it. Its latest figures, published on 19 October 2026, show:
| Period | Average shelf life |
|---|---|
| October 2026 | 13 days |
| September 2026 | 14 days |
| April 2026 (record low) | 8 days |
| 2026 so far | 16 days |
| 2025 | 20 days |
| 2019 | 43 days |
Average fixed rates have also risen. Moneyfacts says the average two-year fix went from 5.59% at the start of September to 5.93% at the start of October, and the average five-year fix from 5.63% to 5.95%.
Why it is happening
Lenders set fixed rates partly using swap rates, which reflect what financial markets expect interest rates to do. Moneyfacts says swap rates have moved with every rumour of peace or escalation in the Middle East conflict, which began at the end of February. When a lender’s costs change, it often reprices or withdraws its deals.
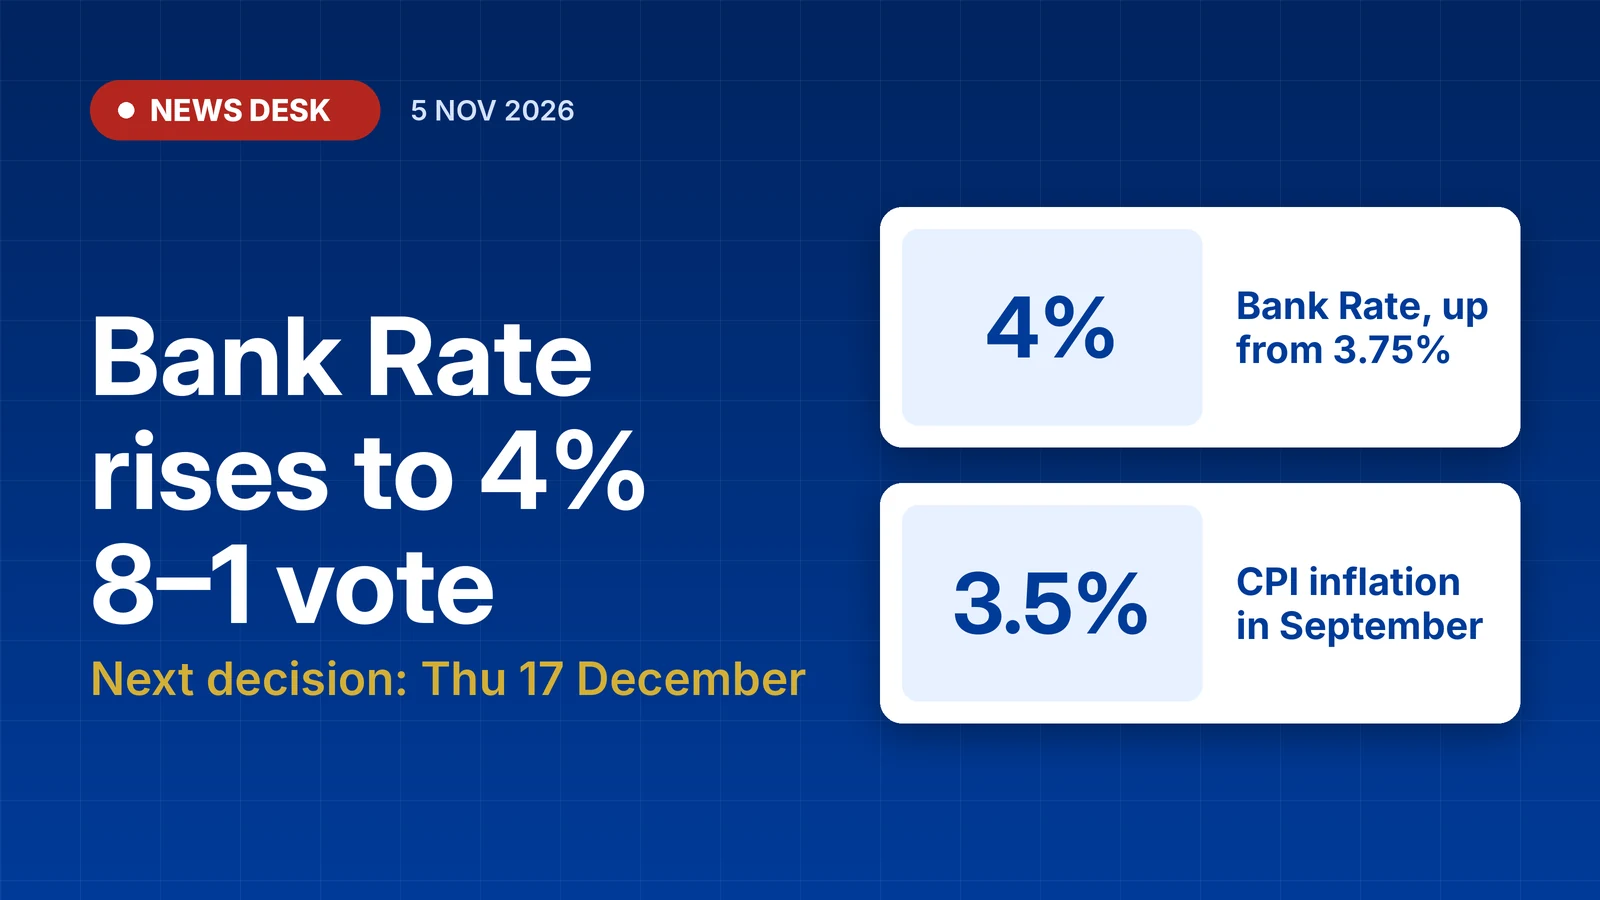
Inflation is adding to the pressure. Consumer price inflation rose to 3.5% in September, up from 3.1% in August. The Bank of England held Bank Rate at 3.75% in September, and its next decision is due on 5 November.
How the rise could affect payments
As an illustration only, on a £200,000 repayment mortgage over 25 years:
- at 5.59%, the monthly payment would be about £1,239
- at 5.93%, it would be about £1,280
That is a difference of about £41 a month. These figures use the Moneyfacts average two-year rates above and are our own calculation. Your own rate and payment will depend on your lender and circumstances.
What this means for you
If your fixed rate ends in the next six months, it may be worth looking at your options now rather than near the end date. Many lenders let you arrange a new deal several months ahead. Because deals are changing so quickly, a rate you see one week may not be available the next.
If you are comparing deals, look at the overall cost, not just the headline rate. Arrangement fees, cashback and early repayment charges can all change which deal works out cheaper.
If you do nothing, most mortgages move on to the lender’s standard variable rate when the fix ends, which is usually higher. Our guide on when and why to remortgage explains the main options.
You can check what a new rate could cost with our free calculator, or set a free reminder so we email you 6, 3 and 1 month before your deal ends. For a personal recommendation, speak to an FCA-authorised mortgage adviser.
For the key dates coming up, see our earlier bulletin: Mortgage Rates: Three Dates to Watch Before 5 November.
Frequently asked questions
Why are mortgage deals being withdrawn so quickly?
Lenders price fixed-rate mortgages partly on swap rates, which reflect what markets expect interest rates to do. Moneyfacts says swap rates have moved with each sign of escalation or calm in the Middle East conflict. When a lender’s funding costs change, it often reprices or withdraws its deals, sometimes at short notice.
How early can I arrange a new mortgage deal?
Many lenders let you arrange a new deal, or switch to a new product with your current lender, several months before your fixed rate ends. Six months is a common window, but it varies by lender. Your current lender’s website or your annual mortgage statement should explain the options available to you.
What happens if I do nothing when my fixed rate ends?
With most lenders, your mortgage moves on to their standard variable rate (SVR) when the fixed rate ends. SVRs are usually higher than fixed rates, so your monthly payment could rise. Checking your end date early gives you time to compare your options, including staying with your lender or moving to another one.
Sources
- Moneyfacts – Mortgage deals available for just 13 days as market remains volatile (19 October 2026)
- Office for National Statistics – Inflation and price indices
- Bank of England – Interest rates and Bank Rate
Published 23 October 2026. This bulletin is general educational information only and is not regulated financial advice. Your home may be repossessed if you do not keep up repayments on your mortgage.
Free reminder service
Is your fixed rate ending soon?
When a deal ends, most mortgages move onto the lender's standard variable rate, which is usually higher. We'll remind you in good time to look at your options.
- 1Tell us when your deal endsJust your first name, email, and the month and year
- 2We email you 6, 3 and 1 month beforeSo you have time to compare, without the rush
- 3Look at your options, no pressureOur guides and calculators are always free
Set up your free reminder
Takes under a minute. Unsubscribe any time.
Your reminder is set
We've sent a confirmation email. If it's not there in a few minutes, check your spam folder.
Mortgage Owl provides general educational information only, not regulated financial advice.
About the author: Steve
Steve is the founder of Mortgage Owl and is training to become a mortgage adviser. He’s currently studying Module 1 of 3 of CeMAP, the Certificate in Mortgage Advice and Practice.
He originally studied business, finance and accountancy, then spent 30 years in policing and the merchant navy before returning to his first passion: helping people make sense of money.
He writes every Mortgage Owl guide in plain English, so you can feel informed before you speak to an adviser.
Qualifications: Registered student with the London Institute of Banking & Finance (LIBF), studying for CeMAP.
He originally studied business, finance and accountancy, then spent 30 years in policing and the merchant navy before returning to his first passion: helping people make sense of money.
He writes every Mortgage Owl guide in plain English, so you can feel informed before you speak to an adviser.
Qualifications: Registered student with the London Institute of Banking & Finance (LIBF), studying for CeMAP.
Related guides
November 1, 2026
October 28, 2026